5 property appraisers in Rotterdam for first-time buyers
Compare five Rotterdam property appraisers for first-time buyers by mortgage brief, evidence, report process, timing and questions to ask.
The best property appraiser in Rotterdam for a first-time buyer is the one that makes the lender brief, property evidence and report handover clear before the deadline.
This shortlist tests five named providers for a first purchase. It uses NHG and independent research as boundaries, while keeping the valuation separate from your income test, bid and lender decision.
TL;DR
Ooms Taxaties, Kettner Makelaars, VENK, JANSS and TOOS are the five researched candidates. Ooms and Kettner publish the clearest mortgage and Rotterdam signals; VENK, JANSS and TOOS add residential credentials that still need a property-specific brief.
Send the accepted offer, lender name, valuation date, deadline and property documents together. Ask who accepts the report before you book an inspection.
Quick overview
What you will find
You will find named providers, the public facts that earned their place, open questions and a weighted fit score. The score helps you decide what to ask next; it does not forecast a valuation.
Selection criteria
Lender and report fit (25 points): 0 = no public evidence; 1 = partial or requires confirmation; 2 = clear evidence in the reviewed material.
Purchase and first-buyer support (20 points): 0 = no public evidence; 1 = partial or requires confirmation; 2 = clear evidence in the reviewed material.
Rotterdam coverage (15 points): 0 = no public evidence; 1 = partial or requires confirmation; 2 = clear evidence in the reviewed material.
Registration and report review evidence (15 points): 0 = no public evidence; 1 = partial or requires confirmation; 2 = clear evidence in the reviewed material.
Process and handover clarity (15 points): 0 = no public evidence; 1 = partial or requires confirmation; 2 = clear evidence in the reviewed material.
Independence and role clarity (10 points): 0 = no public evidence; 1 = partial or requires confirmation; 2 = clear evidence in the reviewed material.
Who this suits
Choose among these providers when you are buying your first Rotterdam home and need to turn a lender request into a workable valuation assignment. The score concerns provider fit; mortgage advice and the loan amount are separate decisions.
How the research works
Each candidate was checked against the same six criteria and the same Rotterdam decision. A 2 means clear public evidence, 1 means partial evidence or a point to confirm, and 0 means the opened material did not establish the point.
Before you book, put the lender’s purpose and report recipient next to a mortgage valuation request before the inspection date is fixed.
If NHG is part of your finance brief, compare NHG physical valuation report requirements with the recipient’s instruction before you set the valuation date. The lender still decides whether the report fits the file.
Related valuation questions
Before you choose, compare the same property, purpose and recipient through property-appraiser quote comparisons so every proposal answers the same brief.
When an accepted offer sets the clock, align the lender deadline with valuation timing when buying a home before you set the inspection date.
Before you compare names, write the property type, purpose, recipient, valuation date and the records that could alter the scope into one brief. That keeps an attractive public signal in its place: it informs the conversation but does not replace the assignment you need.
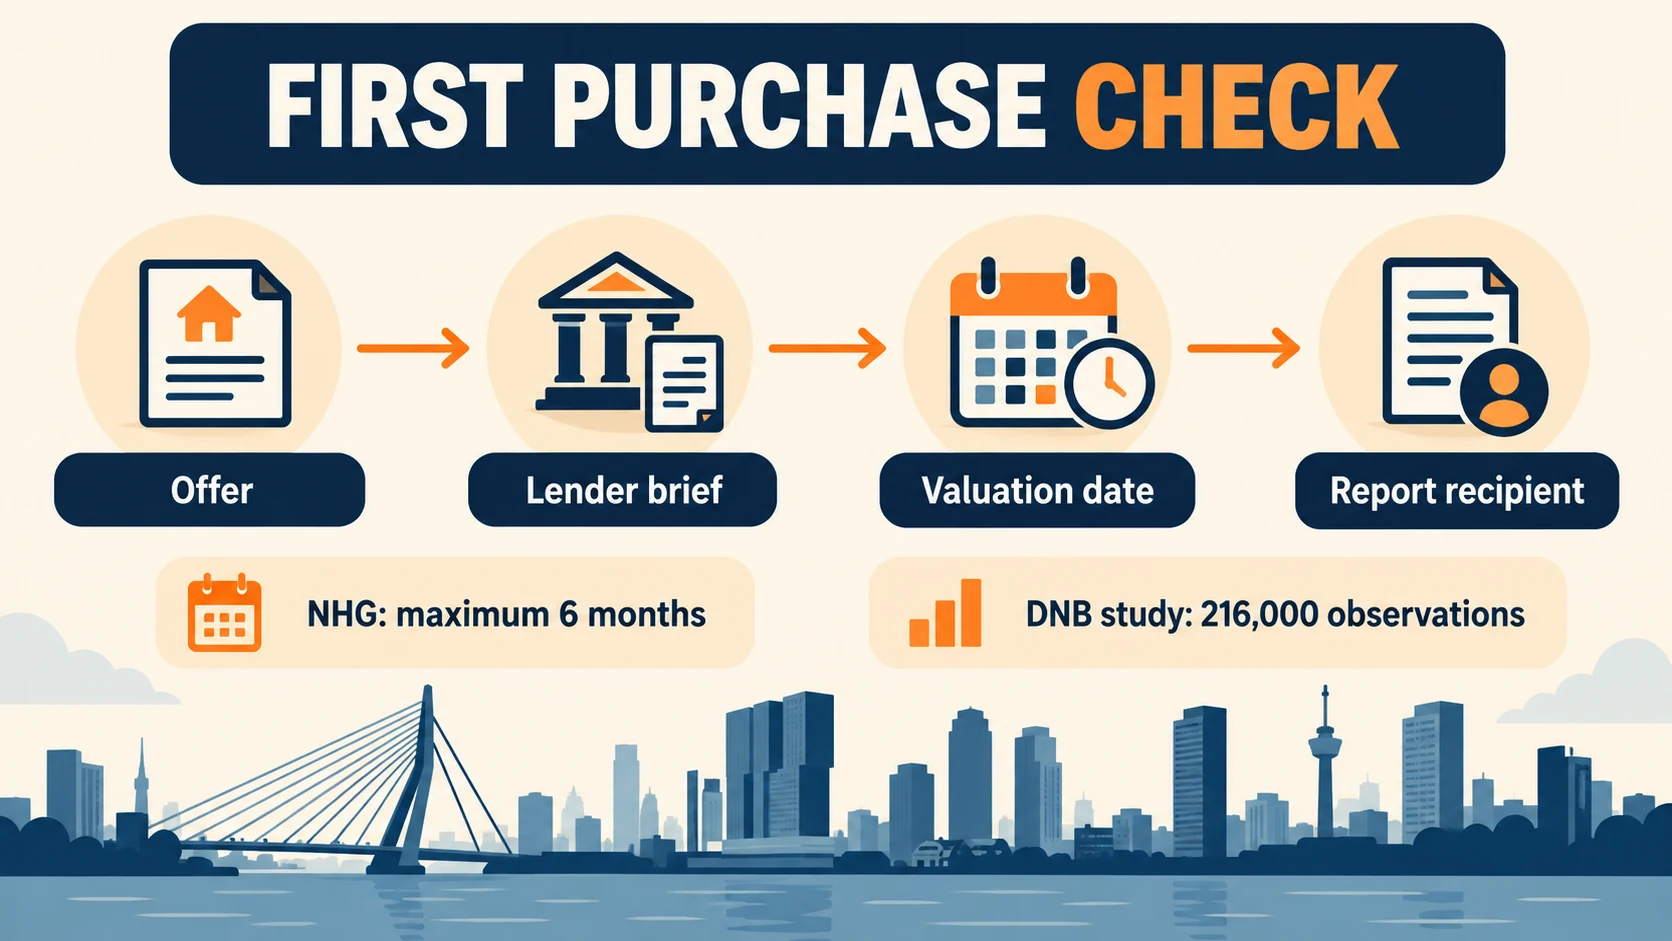
A first-buyer file turns four dates into one sequence: offer, inspection, valuation and lender deadline. The NHG physical-report condition is a maximum age of six months from the valuation date; that rule does not decide every lender file.
Complete shortlist at a glance
Ooms Taxaties: 100/100 fit based on public evidence; A broad Rotterdam residential brief that may involve a mortgage, renovation, refinancing, inheritance or a new construction stage.
Kettner Makelaars: 92.5/100 fit based on public evidence; A Rotterdam residential, mortgage or new construction brief where an urgent appointment or project-stage question needs to be discussed.
TOOS: 77.5/100 fit based on public evidence; A Rotterdam purchase or mortgage conversation where an appraiser who also works as a buying agent may be relevant.
VENK makelaars taxateurs: 92.5/100 fit based on public evidence; A Rotterdam residential mortgage, sale or personal-certainty assignment where a named residential team and multilingual contact are useful.
JANSS. Makelaardij & Taxaties: 87.5/100 fit based on public evidence; A Rotterdam residential valuation where a residential-only profile and NWWI process are useful starting points.
Which provider fits your situation?
Choose among these providers when you are buying your first Rotterdam home and need to turn a lender request into a workable valuation assignment. The score concerns provider fit; mortgage advice and the loan amount are separate decisions.
For a lender-facing residential valuation, start by comparing the public mortgage, NWWI and Rotterdam evidence for all five candidates. For an apartment or new construction home, add VvE or project documents before comparing delivery promises.
Detailed provider breakdown
Ooms Taxaties
Best fit: A broad Rotterdam residential brief that may involve a mortgage, renovation, refinancing, inheritance or a new construction stage.
Public evidence: The residential service describes inspected and validated reports, NVM, Dynamis and Kadaster data, digital delivery and work before or during construction. The Rotterdam office names Senior NVM Register Taxateurs.
Questions to confirm: The reviewed public information gives no universal fee or delivery promise. Confirm the property-specific recipient and timing.
Fit score: Fit score based on public evidence: 100/100. This is a weighted record from 17 September 2026, not a quality or outcome rating.
Kettner Makelaars
Best fit: A Rotterdam residential, mortgage or new construction brief where an urgent appointment or project-stage question needs to be discussed.
Public evidence: The service presents NVM/NWWI valuation work, mortgage and NHG use, independence language and a claimed 48-hour urgent appointment. The business states more than 40 years in the region and a new construction service claims about 330 homes accompanied.
Questions to confirm: The 48-hour and 330-home figures are provider claims tied to stated conditions. Ask whether they apply to your property, fee and recipient.
Fit score: Fit score based on public evidence: 92.5/100. This is a weighted record from 17 September 2026, not a quality or outcome rating.
TOOS
Best fit: A Rotterdam purchase or mortgage conversation where an appraiser who also works as a buying agent may be relevant.
Public evidence: The public profile presents a certified appraiser and buying agent with NVM and NRVT affiliation and mortgage and purchase support.
Questions to confirm: The opened profile does not establish NWWI use, a fee, delivery time or fit for every lender.
Fit score: Fit score based on public evidence: 77.5/100. This is a weighted record from 17 September 2026, not a quality or outcome rating.
VENK makelaars taxateurs
Best fit: A Rotterdam residential mortgage, sale or personal-certainty assignment where a named residential team and multilingual contact are useful.
Public evidence: VENK describes mortgage, sale and personal-use valuations with NVM and NWWI signals. Its Funda profile lists NRVT and NWWI, Dutch, English and German, and 9.3 from 32 reviews.
Questions to confirm: The Funda score does not measure valuation accuracy. The reviewed pages give no universal fee or delivery promise.
Fit score: Fit score based on public evidence: 92.5/100. This is a weighted record from 17 September 2026, not a quality or outcome rating.
JANSS. Makelaardij & Taxaties
Best fit: A Rotterdam residential valuation where a residential-only profile and NWWI process are useful starting points.
Public evidence: The valuation service presents residential-only work, NRVT registration, NWWI guidelines, an inspection and a professional report.
Questions to confirm: The public service page does not establish a first-buyer specialism, fee or standard delivery promise.
Fit score: Fit score based on public evidence: 87.5/100. This is a weighted record from 17 September 2026, not a quality or outcome rating.
Categories
For a lender-facing residential valuation, start by comparing the public mortgage, NWWI and Rotterdam evidence for all five candidates. For an apartment or new construction home, add VvE or project documents before comparing delivery promises.
Situations
A first buyer should separate the purchase price, market value, loan-to-value rule and income test. The lender decides acceptance; the valuer needs a defined property, date, evidence and recipient.
What public pricing shows
No comparable first-buyer fee is published by the five providers. Ask for the full amount and what it includes: inspection, NWWI contribution where relevant, documents, corrections and handover.
Quick reference
Highest weighted fit
Ooms Taxaties leads the matrix for this query; Kettner Makelaars follows. Compare both profiles with your own recipient and property brief.
Most useful specialist question
A first buyer should separate the purchase price, market value, loan-to-value rule and income test. The lender decides acceptance; the valuer needs a defined property, date, evidence and recipient. Ask the candidate to name the evidence and handover conditions in writing.
Lowest public evidence score
TOOS is still included because topic and geography fit are present; its open questions need a direct answer before instruction.
Other researched options
All five named candidates are included in the detailed breakdown. No sixth provider was added without opened, topic-matched evidence.
Comparison cards
-
Assignment: Match the purpose, property, valuation date and recipient before comparing names.
-
Evidence: Match the documents to the property type, rights, condition and use.
-
Credentials: Check the registration or report review requirement that your recipient requires.
-
Handover: Put fee, timing, corrections and follow-up responsibility in writing.
Getting started
-
Write the property, purpose, recipient and valuation date in one brief.
-
Send that brief and the same records to each candidate.
-
Compare missing answers before comparing the total fee.
Checklist before you order
-
Property address and type
-
Purpose and intended recipient
-
Valuation date and delivery deadline
-
Rights, plans, VvE or lease records where relevant
-
Inspection, report review, corrections, fee and follow-up
-
One question for every public claim you rely on
Frequently asked questions
Does the highest score mean this provider is the best for every property?
No. The score records the fit of public evidence for this query on 17 September 2026. Your property, assignment and recipient can change the order.
What should you send before asking for a quote?
Send the address, property type, purpose, intended recipient, valuation date, deadline and records that change the assignment. Add the topic-specific documents named in the shortlist.
Can a public claim settle the decision?
No. Provider claims, review scores, delivery times and prices need a fresh confirmation. The recipient decides whether a report fits the live file.
Why is Ooms Taxaties first in this shortlist?
Ooms Taxaties has the highest weighted fit in the dated matrix for this query. That position reflects public evidence across the six criteria and does not create an endorsement.
Final notes
This shortlist is a dated decision aid. Fees, availability, reviews, report models and recipient rules can change. Confirm the live assignment with the candidate and the party that will use the report.
Take action
Choose two or three names, send the same brief and ask each one to state what is included and what remains open. That gives you a defensible next step without turning public claims into promises.
Send us the property type, lender deadline and the report condition you do not understand. We can help you frame a general question before the appointment; leave out identity documents, bank details and sensitive files.Ask about a first-buyer valuation