NWWI valuation report: how validation fits the Dutch mortgage file
Understand what NWWI validation checks in a Dutch valuation report and what remains for the appraiser and lender to decide.
TL;DR
Are you preparing a Dutch mortgage file? NWWI review checks a valuation report against set requirements. It does not decide the value or approve your mortgage. The appraiser remains responsible for the opinion; the lender decides whether the report fits the loan file.
Before you request the report, write down the purpose, recipient, property, value date and lender instruction. That gives you a clear test for the report you need.
Prepare the assignment
If a lender is involved, compare the recipient’s brief with Amsterdam valuation report contents before you treat a report as complete.
If a lender requests an NWWI review, compare the valuer’s opinion with NWWI requirements before treating the review decision as part of the valuation itself.
When the report is for a lender, keep the assignment tied to a Dutch mortgage valuation report so its recipient conditions remain visible.
Ask the lender or adviser which report type it accepts and whether NWWI review is required. Record the answer with the property address and deadline.
Prepare a compact file:
- purchase agreement or the reason for the report;
- address, property type, ownership and tenure details;
- floor plans, measurements and known alterations;
- ground lease, VvE, permit and energy documents where relevant;
- planned work and the assumption about completion;
- intended recipient and required value date.
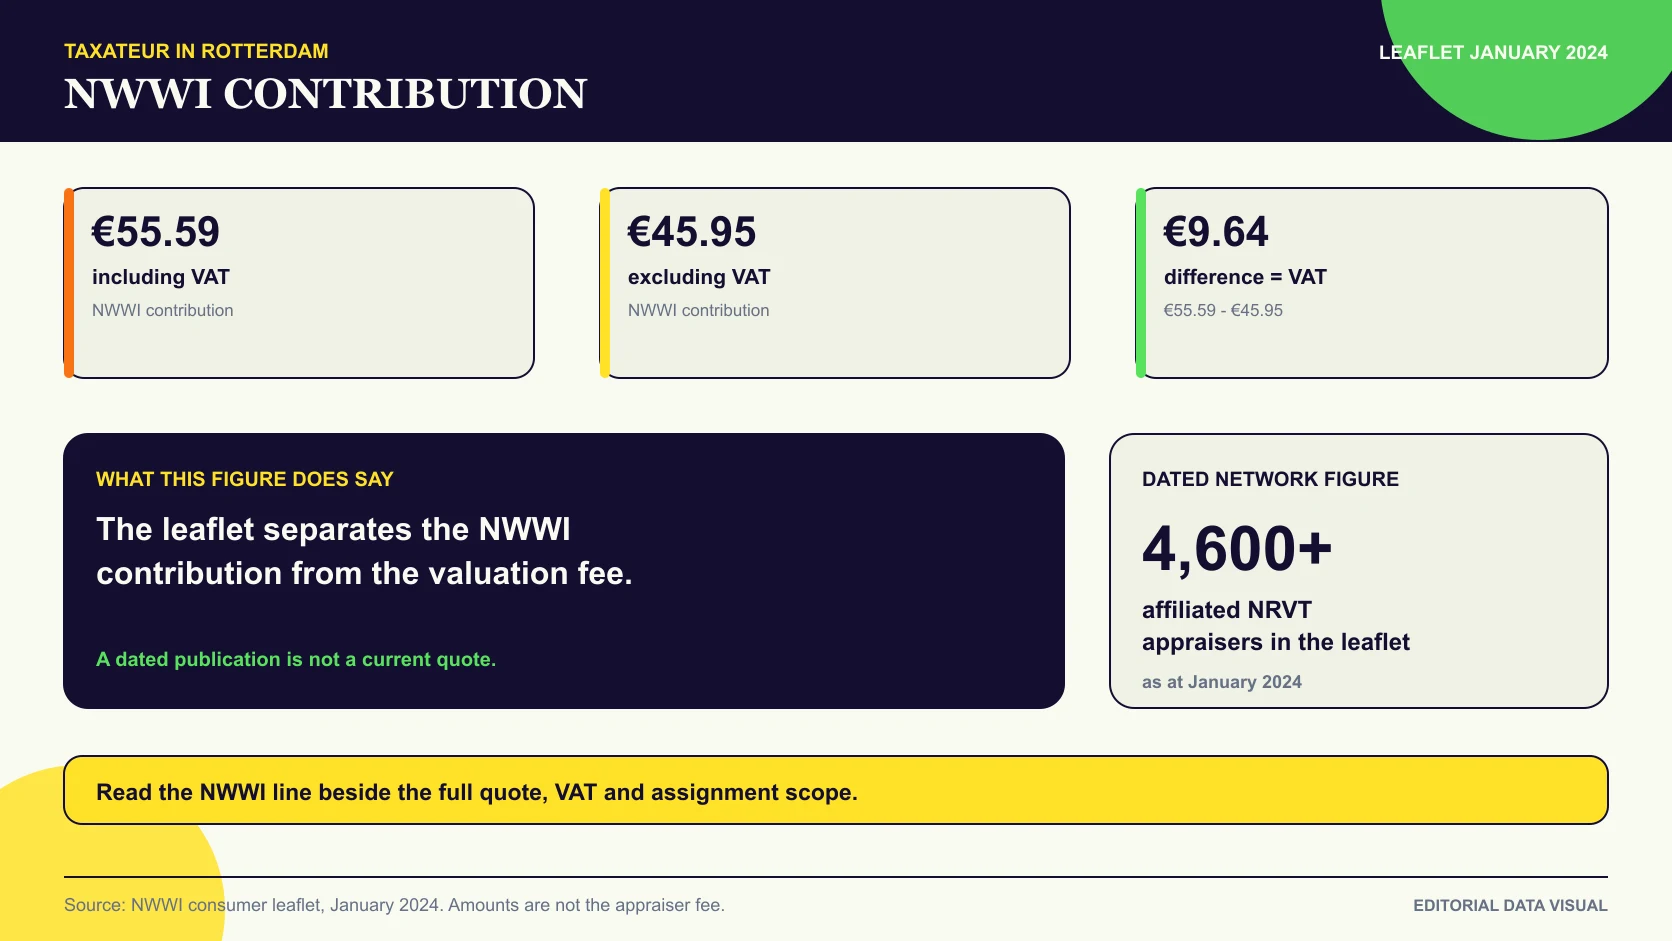
The NWWI consumer leaflet describes NWWI review as a check of the report and the registered appraiser against quality requirements. That description gives you a useful boundary: NWWI review concerns the report file, while the lender’s credit decision has more inputs.
The NWWI review sequence
1. Define the question. A report for purchase, refinancing or renovation can require a different brief. The recipient and date belong in the first message.
2. Let the appraiser investigate. The appraiser reviews the home, supplied documents and comparable evidence. Mark missing papers or unresolved permission as an open point.
3. Review the report. Check the property description, value date, purpose, recipient, comparable sales, adjustments and assumptions. If the report refers to an attachment, find it before forwarding the file.
4. Read the NWWI review outcome. Keep the NWWI review result with the report. If a point is queried or changed, ask who must correct it and whether a new NWWI review step is needed.
What to check in the returned report
Use page references rather than a general feeling that a report is too short.
- Does the address match the purchase agreement?
- Does the stated purpose match the lender’s instruction?
- Are value date, inspection date and report date visible?
- Are comparable homes described with enough context to understand the comparison?
- Are renovation, lease, VvE and permit assumptions marked?
- Is the recipient correct?
- Does the NWWI review result describe a quality check rather than a loan promise?
NHG states that a physical report in its context must be made independently, validated by an accepted institute and be no more than six months old from the valuation date. A lender can request delivery sooner. Keep the NHG condition and the lender’s own date rule in separate notes.
Rijksoverheid says a mortgage can generally be no more than 100% of the home’s value, alongside income and debt rules. A validated report can inform the value side of the file; it does not complete the borrowing assessment.
What NWWI review does not prove
A validated report does not prove that a purchase price will be accepted. It does not remove market uncertainty after the value date. It does not certify construction quality, settle a permit question or replace a WOZ decision.
A low value can still be correctly reasoned. Read the comparable selection and adjustments before asking for a correction. A difference from an online estimate is also not enough to show an error; the products can have different dates, purposes and evidence.
No universal delivery promise applies. Timing depends on the assignment, documents, appraiser and NWWI review queue. Ask the appointed professional for the current hand-in plan.
Frequently asked questions
Does NWWI calculate the value?
The appraiser makes the valuation opinion. NWWI checks the report and appraiser against its NWWI review requirements.
Is NWWI review required for every home valuation?
The answer depends on the recipient and report type. Ask the lender or other intended recipient.
How old can the report be?
In an NHG physical-report context, NHG describes a six-month maximum from the valuation date. Your lender can require an earlier hand-in.
Can NWWI review fix a missing document?
The report may need a correction or an additional document. Ask the appraiser who owns the correction and whether the amended report needs another check.
Send a NWWI review question
Use the English contact form for a general question about a report line, recipient, valuation date or validation result. Include the purpose and page reference, without sensitive documents.Ask about NWWI validation